

The precious metals bull market began in earnest two years ago, when gold finally awoke from its long slumber and surged decisively above $2,000, a breakout I foresaw and alerted about just days before it began.
Since then, I’ve devoted a significant amount of time and energy to explaining why this secular bull market in precious metals, including mining stocks, is still in its early stages. I expect it to last at least a decade, with gold eventually reaching $20,000+ and silver $500+. Until those conditions are met, I have no interest in negativity, bearish takes, or selling my holdings.
In sharp contrast to my optimism and firm belief in this precious metals bull market, skepticism, cynicism, and fear has been the dominant sentiment among investors nearly the entire way up. Bull markets are said to climb a “wall of worry,” and this one certainly has and continues to do so.
Every few weeks, it seems, a new theory or rumor emerges about what will finally cause the bull market in gold, silver, and mining stocks to peak and roll over into a devastating bear market that quickly erases the gains of the past couple years.
For example, in early November many investors claimed that gold and silver had topped out after reaching $4,400 and $54, respectively, and that a major crash was imminent. I argued the exact opposite, however, and even called the precise bottom before the next leg higher, which ultimately carried prices to $5,600 and $121 in the coming months.
Then in early January, the concern shifted to the rebalancing of the Bloomberg Commodities Index. Many argued that the forced selling of gold and silver would finally break the back of the bull market. I dismissed that theory outright and was proven correct. Instead of collapsing, precious metals actually surged during the rebalancing period.
Then there was the sharp correction in precious metals and mining stocks in late January, which led many investors to believe that the generational peak had finally arrived, similar to what occurred in 1980 and 2011, and that it was all downhill from there. I disagreed, however, arguing that the decline was simply an emotionally-driven blip and that the long-term secular bull market remained intact. Since then, prices have recovered nicely, and I expect that recovery to continue with new highs reached in the not-too-distant future.
As you can see, there is a consistent pattern of fear. Investors are constantly asking, “When will the crash happen?” “Is this the crash?” “Is a crash coming soon?” “Can you give me a heads-up before it happens?”
It’s a constant fixation on crash, crash, crash. It reminds me of kids on a road trip repeatedly asking, “Are we there yet?”
From a contrarian standpoint, that level of fear and skepticism is typical of the early stages of a bull market, which is where I believe precious metals are today. It is not what you see in a mature bull market, when fear of a crash largely disappears and greed becomes the dominant emotion.
So now I want to explain why I’ve remained so calm during the pullbacks, corrections, volatility, and consolidations we’ve seen in precious metals over the past two years. It’s not because I’m a “permabull” who will always be bullish on precious metals, even in the face of genuine risks and the eventual end of the secular bull market.
To put it simply, I’ve remained calm and optimistic because I pay very close attention to where precious metals stand in the bull market cycle. For the past two years, including today, they have remained extremely early in that cycle both in terms of time and valuations, and I’m going to prove that in this report.
Because I know the bull market in precious metals is extremely young with many more healthy years left, I confidently brush off scary rumors and technical pullbacks along the way up.
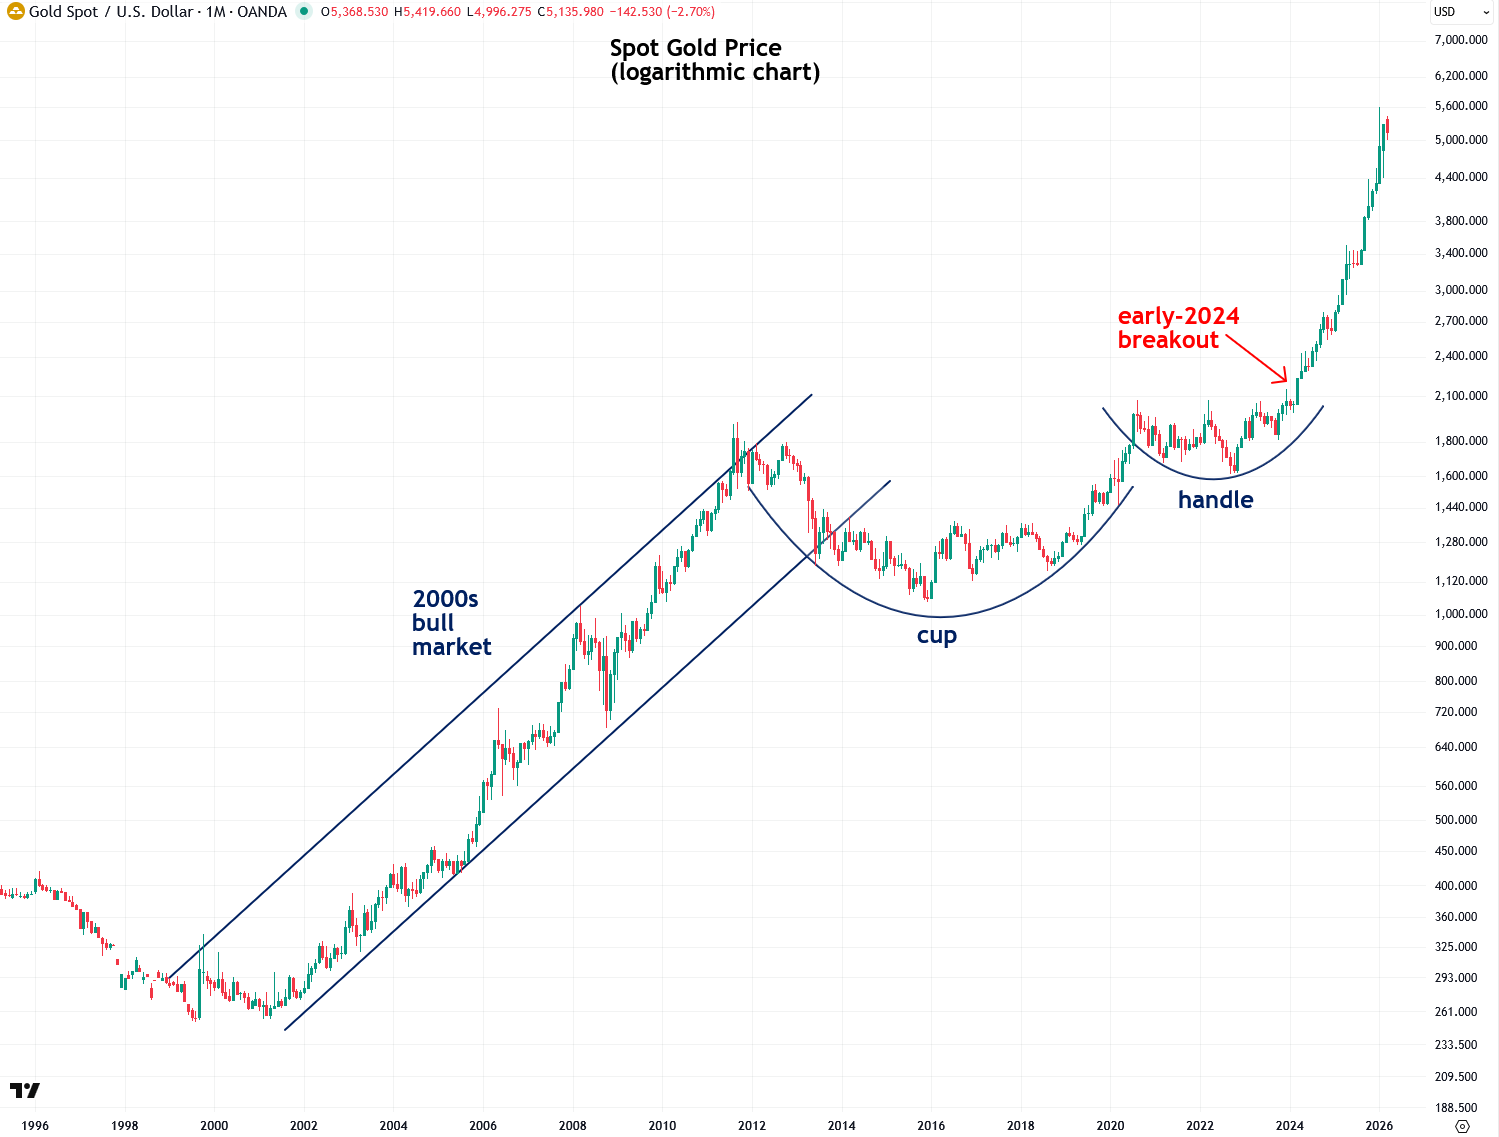
In order to better understand where precious metals are in the bull market cycle, let’s start with the long-term logarithmic chart of gold. I’m focusing on gold because it leads the overall precious metals complex.
As you can see, just two years ago gold broke out of a cup-and-handle pattern that had been forming for twelve years. A breakout from such a long pattern should last well beyond two years and should at least match the early 2000s bull market, which lasted more than a decade.
So now let’s get into the meat of my thesis, which is that despite the strong nominal gains in gold over the past two years, it’s more meaningful to compare gold to other assets rather than view it in isolation. One of the most important benchmarks is the U.S. stock market because stocks and gold have a long-established relationship in which capital rotates between the two over long periods, typically lasting at least a decade.
To illustrate this phenomenon, I created the logarithmic chart below of the gold-to-Dow ratio going back to the late 1930s. I use the Dow because it has the longest history of any major U.S. stock index.
When the ratio is increasing (periods when there are gold-colored trendlines), gold is gaining in price relative to stocks. When the ratio is decreasing (periods when there are green-colored trendlines), stocks are gaining relative to gold. A new cycle begins when a major generational trendline, either gold or green, is broken, triggering a reversal of the conditions that defined the previous cycle.